Transportation
Still have the original Chase Freedom? Here’s why I switched to the Freedom Flex
I’ve had the legacy Chase Freedom®* since 2017, and for years, it was one of those cards I had no…
Category Added in a WPeMatico Campaign
I’ve had the legacy Chase Freedom®* since 2017, and for years, it was one of those cards I had no…
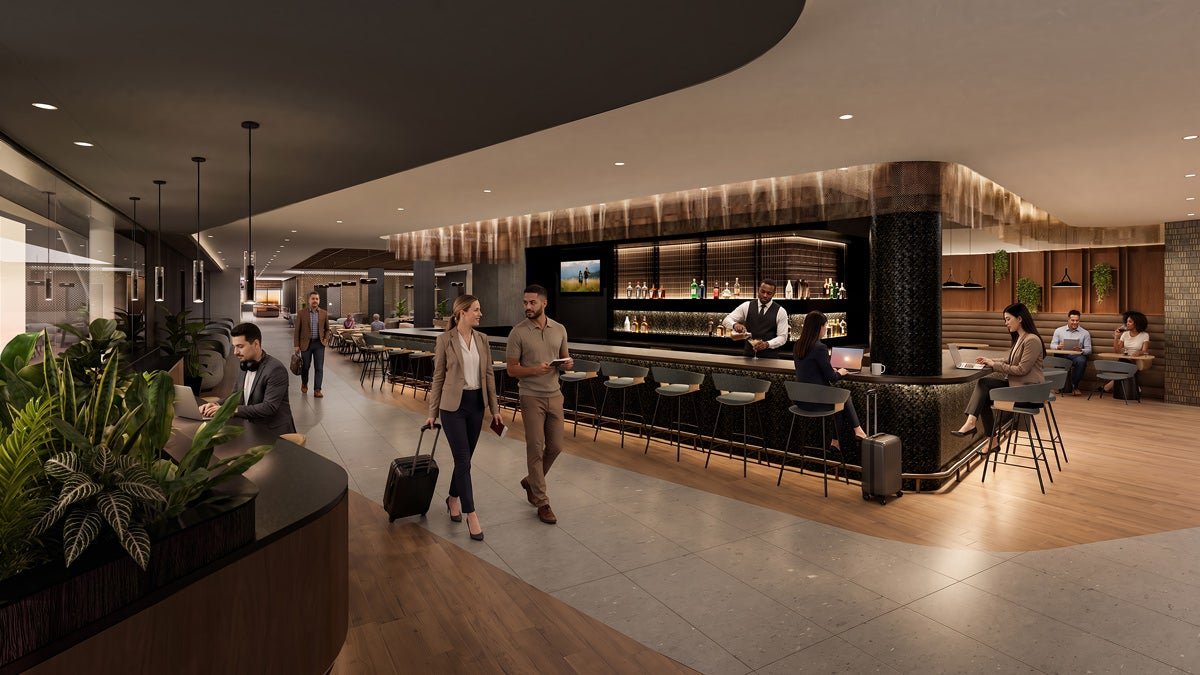
Could this be the most badly needed airport lounge in America? You could certainly make that argument about American Airlines’…
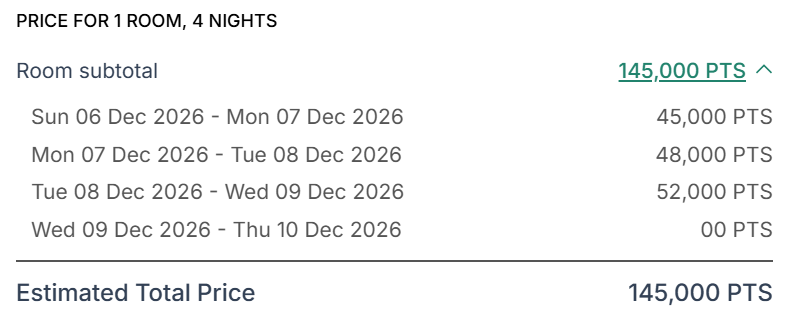
The IHG One Rewards Credit Card (see rates and fees) is IHG’s no-annual-fee card option. With this card, you can…
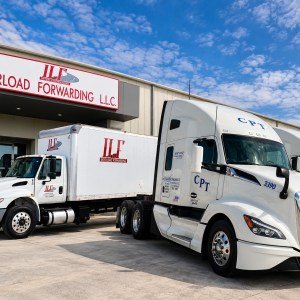
TA Services has acquired two Texas trucking and logistics companies, adding more than 130 trucks and 550,000 square feet of warehousing to its growing U.S.-Mexico cross-border network. The Mansfield, Texas-based third-party logistics provider announced Tuesday it acquired the assets and operations of Carmen Pacheco Transportation LLC (CPT) and Interload Forwarding LLC (ILF). Financial terms of the transactions were not disclosed. The deal expands TA Services’ transportation and warehousing operations in El Paso and Laredo, Texas, two major gateways for freight moving between the U.S. and Mexico. The transaction includes trucking assets, five warehouses and a truck yard covering about 10 acres. Federal Motor Carrier Safety Administration records show the two carriers operate a combined 133 power units and employ 123 drivers. El Paso-based CPT operates 61 power units and has 57 drivers, according to FMCSA’s database. The carrier reported nearly 8.3 million miles traveled in 2024 and has active interstate operating authority. FMCSA records show CPT hauls general freight, dry bulk commodities, beverages and paper products. ILF, which lists an address at the same El Paso industrial complex as CPT, operates 72 power units and employs 66 drivers. The company reported about 1.6 million miles traveled in 2024 and also holds active interstate authority as a for-hire property carrier. ILF reports hauling general freight, beverages, paper products and electronics. Together, CPT and ILF provide local and long-haul trucking, warehousing, cross-docking, freight consolidation and deconsolidation, brokerage and customs-related services, according to TA Services. “Cross-border performance depends on what happens on both sides of the border and at every handoff in between,” TA Services CEO Scott Schell said in a news release. Schell said the acquisitions strengthen TA’s ability to serve manufacturers and other shippers moving freight through the U.S.-Mexico corridor. “Bringing our teams together gives us a stronger foundation to serve manufacturers and other shippers moving freight through the U.S.–Mexico corridor,” Schell said. “As the industrial economy continues to expand in 2026 and over the years to come, we are setting ourselves up to be a key partner to support this growth.” Family-owned carriers will remain involved CPT and ILF grew from a family enterprise founded by Richard Ibarra Sr. The companies’ employees and members of the Ibarra family will remain involved following the acquisition, according to TA Services. “We built these companies by knowing our customers, keeping our word and taking care of the freight entrusted to us,” Ibarra said in a statement. “We are excited to partner with TA. This gives our customers access to more markets and services, and it gives our employees a place to work and grow under a strong brand that shares our commitment to service.” The acquisitions mark a significant expansion of TA Services’ existing cross-border strategy. TA Services, the non-asset flagship division of PS Logistics, provides multimodal brokerage, managed transportation, warehousing and cross-border logistics across the U.S., Mexico and Canada. TA executives have previously identified Mexico’s manufacturing sector as a long-term driver of freight demand. Miguel Perez, TA Services’ senior director of cross-border operations and solutions, told FreightWaves in January 2025 that Mexico would remain attractive for manufacturers despite uncertainty surrounding tariffs. “Even with the tariff’s taking effect, Mexico will still represent a very attractive option,” Perez said. Why it matters: The acquisitions give TA Services a larger physical presence at two of the most important gateways for truck freight between the U.S. and Mexico. The post TA Services acquires 2 Texas cross-border carriers, adds 133 trucks appeared first on FreightWaves.
The US is planning a lot more gas power – and data centers are the culprit. Proposed grid-connected gas capacity has nearly tripled since early 2023, while plans for new wind power are shrinking. more…
#fwtv_oNkz0zF2IjU .fwtv-panel{border:1px solid #d0d0d0;padding:18px;border-radius:6px;line-height:1.6}#fwtv_oNkz0zF2IjU .fwtv-panel p{margin:0 0 12px}#fwtv_oNkz0zF2IjU .fwtv-note{font-style:italic;color:#666;margin-top:16px;padding-top:12px;border-top:1px solid #e0e0e0}The freight market is experiencing an unprecedented capacity crisis, with carriers rejecting loads at four times the normal rate despite stable volumes. This isn’t a typical demand-driven cycle; instead, capacity is exiting the market faster than new trucks can enter, driven by escalating costs, driver shortages, and regulatory hurdles. Discover why the market will remain tight and what shippers and brokers should be watching.Tender rejection rates have surged to roughly 14% — about three times their 2023 levels — while truckload volumes over the past three years are up only 9%, according to a Tuesday Sonar market update by Julie Van de Kamp. The divergence means carriers are rejecting nearly four times as many loads on roughly the same amount of freight, a dynamic that signals a structural supply problem rather than a demand-driven cycle. “The price signal is there, but capacity response isn’t,” Van de Kamp said. Total for-hire tractors fell approximately 51,000 in August alone, and new fleet tractor counts — which peaked at about 47,000 in mid-2022 — have been declining rather than recovering despite a full year of elevated rejections. “Carriers are rejecting nearly four times as many loads on roughly the same volume. In a normal cycle, that gap closes as new trucks enter and rejections fall again, but it hasn’t closed.” Net carrier authority additions have turned positive in 2026 and hit a five-year high above 2,000 per week in late August and September, but Van de Kamp cautioned against reading those figures as evidence of real capacity growth. In the last capacity boom, authorities rose 51% while actual tractor counts rose only 12%. She also attributed much of the 2026 spike to noise around the FMCSA’s new MOTIS system, which paused deactivations and cleared application backlogs. Estimated new authority grants actually ran about 17% below first-quarter levels, and only about two in three new interstate registrants purchased liability insurance — compared with nine in ten during the 2019 cycle. Driver availability is a compounding constraint. More than 202,000 CDL holders are sidelined for drug and alcohol violations, the non-domiciled CDL rule affects more than 194,000 drivers over time, and English proficiency enforcement is removing roughly 2,700 drivers from service each month. Schneider specifically described the market as driver-constrained in its most recent earnings, while Knight-Swift and Werner said driver availability is limiting fleet growth, shifting their focus to yield and utilization instead. Cost pressures are also blocking new entrants. Insurance premiums rose about 4% in 2025 and another 4% to 6% in early 2026 even as crash rates decline, driven by liability and litigation exposure. Diesel costs continue to strain small carrier cash flow. About 10% of carrier trucks are parked, Van de Kamp noted, but those units can only return to service if compliant drivers are found — an outlet she does not currently see. Van de Kamp said she expects the market to remain tight at least through early 2027, and potentially considerably longer, even without a demand spike. For shippers and brokers, she recommended ignoring net authority headlines and instead tracking tractor counts, fleets reporting miles, and the gap between tender rejections and tender volumes as the leading indicator of any eventual capacity turn.Tender rejections are near 14% — roughly 3x their 2023 levels — while truckload volume is up just 9% over three years, with carriers rejecting nearly 4x as many loads on similar freight.Net carrier authority additions hit a 5-year high above 2,000 per week, but actual tractor counts fell ~51,000 in August; in the last boom, authorities rose 51% while tractors rose only 12%.Over 202,000 CDL holders are sidelined for drug/alcohol violations and 2,700 more are removed monthly for English proficiency, with insurance costs up 4–6% in early 2026, blocking new capacity entry.This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above. The post Trucking Capacity Crisis: Rejections Up 4x on Same Volume appeared first on FreightWaves.
#fwtv_uwgYjsrNTnY .fwtv-panel{border:1px solid #d0d0d0;padding:18px;border-radius:6px;line-height:1.6}#fwtv_uwgYjsrNTnY .fwtv-panel p{margin:0 0 12px}#fwtv_uwgYjsrNTnY .fwtv-note{font-style:italic;color:#666;margin-top:16px;padding-top:12px;border-top:1px solid #e0e0e0}Chris Wofford joined FW Today to talk freight, macro risk and what operators should actually be watching right now. No hype, no magic-timeline calls—just the signals that matter if you run trucks, buy capacity or sit in the middle. What are you watching most?C.H. Robinson’s acquisition of RXO is the largest truck brokerage merger-and-acquisition transaction in history, catching even veteran deal advisers off guard. The deal, announced this week, centers on $300 million in projected synergies that C.H. Robinson CEO Dave Bozeman presented to investors — a figure that analysts say dwarfs the target’s existing EBITDA base and will drive quarter-by-quarter scrutiny from the S&P and shareholders alike. The transaction surprised market watchers in part because RXO was widely viewed as a future acquirer, not a seller. “I think Drew and the team were well down the path of the integration on Coyote, and obviously they’d increased the synergy estimates repeatedly. And I think we viewed them as a future serial acquirer once they got their debt levels down,” said the M&A adviser who joined FreightWaves Today to analyze the deal. He noted the transaction was kept unusually quiet and “happened very fast,” with only minor unusual options activity detected a few days before announcement. On a pro forma forward basis, the deal prices at roughly 10x EBITDA — in line with market precedent, according to the adviser. He said Robinson is likely the only strategic buyer capable of generating synergies at this scale, a dynamic reflected in the break fee, which he estimated at approximately $1 per share, signaling the market sees little risk of a competing bid. “The synergies are just massive here in comparison to the size of the EBITDA of the target. So, what does that mean for the stock going forward? Well, obviously, everybody’s going to be zeroed in on the rollout of those synergies and achievement levels quarter by quarter by quarter.” The deal raises a structural question for the broader brokerage market: how much room remains to grow? U.S. truckload brokerage outsourcing sits at roughly 25% to 30%, compared to a declining growth curve that becomes visible in markets like the U.K. around 40% to 50% penetration. The adviser said the U.S. market remains in “the middle innings” of growth, particularly with freight rates firming and yields improving — factors he said make the timing of the Robinson-RXO combination strategically notable. The transaction is expected to accelerate M&A activity more broadly, though the list of credible large-scale acquirers is thin. Echo Logistics, which filed a confidential S-1 for an eventual IPO, was cited as a potential future roll-up player once public. TQL, ranked second among U.S. brokers, was flagged as a wildcard despite having no recent M&A track record. The adviser also identified several billion-dollar-plus assets — including Redwood Logistics, TI Nolan, and Mode — as likely to trade within the next 24 months, either to strategic buyers or sponsor money. International players such as DSV, which he described as “underrepresented in the North American market” especially following its Schenker acquisition, were also named as potential entrants. The adviser cautioned that the Robinson deal’s knock-on effects may be most pronounced in the mid-market. A company currently ranked around 20th could execute a few targeted acquisitions and emerge as a top-10 player — a path he compared to RXO’s own ascent through the Coyote deal. At the top of the market, however, he said the catalyst for additional mega-deals is less obvious than the initial wave of commentary suggested. “I think there’s going to be a lot of smaller truckload brokers are going to come to market. There’s going to be a mid-sized one. There’s going to be a few larger ones,” he said, adding that warehousing M&A is accelerating alongside ground brokerage consolidation.C.H. Robinson’s acquisition of RXO is the largest truck brokerage M&A deal in history, anchored by $300 million in projected synergies that will be tracked quarter by quarter.U.S. truckload brokerage outsourcing is only 25% to 30%, suggesting the market remains in ‘the middle innings’ of growth despite accelerating consolidation at the top.The most likely near-term M&A activity will occur in the mid-market tier, with several billion-dollar-plus assets including Redwood Logistics and Mode expected to trade within 24 months.This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above. The post Freight’s Next Move Matters More Than the Last 18 Months appeared first on FreightWaves.
Old Dominion Freight Line was named the top national less-than-truckload carrier for a 17th straight year while Daylight Transport received top overall honors for a third straight year, according to a news release from Mastio & Co. The research and consulting firm annually conducts the industry’s most comprehensive survey evaluating customer value and loyalty. This year’s results were based on 1,647 telephone interviews with LTL shippers from June through September. Respondents provided approximately 5,300 evaluations, rating 155 carriers, with 24 earning ratings sufficient to make the report. Key decision makers were asked open-ended questions about carrier service offerings, competitiveness and customer retention. The rankings are historically based on 28 service metrics, including on-time delivery, damages, transit times, pricing and technology, as well as back-end functions like billing accuracy, claims processing, problem resolution and carrier responsiveness. Thomasville, North Carolina-based Old Dominion (NASDAQ: ODFL) said it ranked No. 1 in 24 of the evaluated service categories, “including carrier trustworthiness, ease of doing business, timely customer service, and shipments delivered when promised.” “This award is very important to us because it is selected by shippers,” said Marty Freeman, president and CEO of Old Dominion, in a Tuesday news release. “They count on OD to do more than just move their freight – we are an extension of their brand and true business partners.” Two other national carriers—privately held Estes and publicly traded XPO (NYSE: XPO)—also exceeded the industry benchmark for national operators. Richmond, Virginia-based Estes was named best value provider among national carriers for a fifth consecutive year. It also received the top ranking for competitive pricing and website usefulness. The carrier, like others, has been actively increasing its door count to enhance its service offering. “These results offer a meaningful perspective on how shippers experience Estes — from the value they receive to the people and tools they interact with every day,” the company said in a statement. “We’re proud of this feedback and will continue to listen, improve, and find new ways to make the shipping experience even better for the people we serve.” Greenwich, Connecticut-based XPO recorded the largest year-over-year increase in net promoter score and weighted performance score among all national carriers. The carrier’s recent quarterly earnings report validated these improvements. Cypress, California-based Daylight Transport was also named the top inter-regional carrier in addition to top overall honors. Repeat regional winners included: Pitt Ohio (Northeast/Mid-Atlantic), Dayton Freight Lines (Great Lakes/Midwest) and Peninsula (Western). Averitt Express was the overall winner in the Southern region. Why it matters? Mastio’s annual survey provides a comprehensive, data-backed benchmark of carrier performance across key service metrics like on-time delivery and pricing. Additionally, it highlights market leaders and direct shipper feedback, giving companies valuable insight into the service standards and customer expectations that drive carrier selection. More FreightWaves articles by Todd Maiden: Transportation prices surge as capacity tightens further in September STG Logistics announces new CEO, board members Hub Group reshuffles board amid accounting turmoil The post LTL survey: Old Dominion, Daylight Transport take home top honors again appeared first on FreightWaves.
#fwtv_6EOf3ug97FY .fwtv-panel{border:1px solid #d0d0d0;padding:18px;border-radius:6px;line-height:1.6}#fwtv_6EOf3ug97FY .fwtv-panel p{margin:0 0 12px}#fwtv_6EOf3ug97FY .fwtv-note{font-style:italic;color:#666;margin-top:16px;padding-top:12px;border-top:1px solid #e0e0e0}A staggering $100 billion discrepancy exists between China’s reported exports and the US’s recorded imports. Michael Kanko, CEO of ImportGenius.com, explains what this trade data delta signifies for the global supply chain. He details how granular shipping records are used for everything from sourcing new components to ensuring compliance with international sanctions, and why transparency in air cargo data is the next big battle for US manufacturers.ImportGenius has identified a more than $100 billion gap between what China reported shipping to the United States last year and what U.S. records show as received — a discrepancy that highlights the limitations of relying on government trade statistics alone and the growing role of bill-of-lading data in supply chain intelligence. The finding emerged when ImportGenius normalized its shipment-level data into TEUs — the standard 20-foot equivalent unit used in global container trade — and cross-referenced that count against U.S. Census dollar values to derive a value-per-container figure. Comparing that metric to China’s own TEU-normalized figures produced what the company described as a major and “mystifying” difference. Possible explanations include transshipment through third countries such as Vietnam, incorrectly recorded shipment values, and potential incentives tied to tariff optimization. “Some of the incentive in this might simply be related to tariff and optimizing for tariff bills,” said Michael Kanko of ImportGenius. Beyond the macro discrepancy, Kanko said the platform’s users are increasingly tapping shipment records — which capture details down to the markings on individual boxes, container contents, shipper and consignee identities, and notified parties — for sourcing and compliance purposes. With sanctions at historically high levels due to ongoing conflicts, companies are using trade data to vet new customers. Kanko offered a concrete example: confirming whether an aviation parts buyer in Turkey had transacted with Russia within the past 30 days. Law enforcement and brand-protection teams, including major footwear manufacturers tracking counterfeit sneakers from Asia, are also users. On near-term freight volumes, Kanko said he expects international ocean shipping activity to continue, and possibly intensify, through at least the midterm elections, citing persistent policy uncertainty as the primary driver. He also noted rising shipment activity out of Vietnam, Mexico, and other Asian and South American origins. ImportGenius recently gained access to Mexican shipment-level trade data, which also provides visibility into transborder land crossings between Mexico and the United States. An emerging use case is domestic lead generation: U.S. manufacturers are now using the platform to identify importers of products similar to what they produce — essentially building prospect lists at a moment when the pricing dynamic has shifted in their favor relative to Chinese competitors. Kanko said this trend is notably stronger than when the company was founded nearly 20 years ago. The company is also pushing for legislative change on air cargo transparency. Nearly half of U.S. imports by value arrive by air, yet no public manifest data exists for those shipments — a gap Kanko attributed to a law rooted in maritime trade that has not kept pace with air cargo’s growth since the 1970s. ImportGenius has spent three years advocating for the Manifest Modernization Act, which has companion bills in both the House and Senate and support from the Ways and Means Committee, the Senate Finance Committee, and the House China Select Committee. Kanko testified before the Ways and Means Committee and said the bill has drawn bipartisan co-sponsors. The company is also exploring whether the legislation could be attached to the annual defense reauthorization bill before year’s end.ImportGenius found a $100B-plus gap between China’s reported exports and U.S. import records, with tariff optimization cited as one possible explanation.Nearly half of U.S. imports by value arrive by air but carry no public manifest data; the bipartisan Manifest Modernization Act aims to close that blind spot.U.S. manufacturers are increasingly using shipment-level trade data for lead generation as the pricing dynamic shifts away from Chinese suppliers.This Summary is generated thanks to a transcription of the interview, for the full interview please enjoy the video above. The post $100B Trade Gap: China vs. US Data Exposed appeared first on FreightWaves.
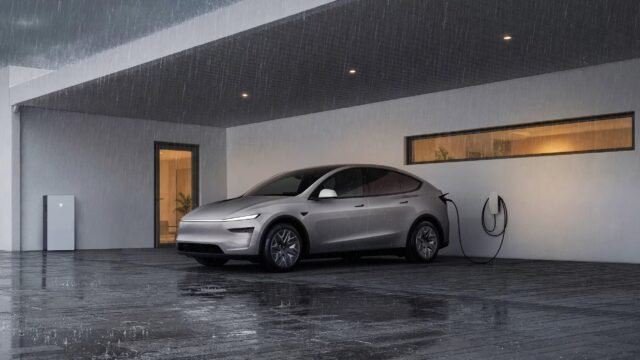
Some Tesla Model 3 and Model Y owners can use their EV battery to keep the lights on longer during a power outage, now that Tesla's expanding the Powershare Home Backup feature. It was previously only available on the Cybertruck, and also requires owning Tesla's Powerwall 3. However, support for the Powerwall 2 and Powerwall Plus is "coming soon." Tesla's EVs aren't the first or only ones with bidirectional charging; companies like Kia and GM also offer vehicle-to-home power on their vehicles, while Nissan's Leaf offered power-to-grid charging years ago. Tesla says the Model 3 and Model Y can extend home backup power to over two days for Pr … Read the full story at The Verge.