My car battery died as I was leaving for the airport — Chase’s roadside assistance arrived in 8 minutes
Transportation
It’s a feeling no one wants to experience.You’re all set to leave the house. The kids are loaded, the electronic devices are charged and the car is gassed up. You go to start it up, and … nothing. Your battery has died.This exact thing happened to me earlier this month, but mine has a happy ending. That’s because I called Chase and requested roadside assistance, a benefit on my Chase Sapphire Reserve® (see rates and fees).And, amazingly enough, a service technician arrived at my house exactly 8 minutes after I placed the request.Here’s my story — and how you might be able to use the same perk on one of your cards.A dead battery — and a failed call to AAAMy story begins just minutes before I was set to leave for the airport on a business trip. I had loaded my suitcase and said goodbye to my wife and daughter. Unfortunately, the car wouldn’t start. And the clicking noise made me pretty sure it was the battery.Thankfully, my drive to the airport wasn’t super time-sensitive; I was spending the night there before an early-morning departure. Nevertheless, I was nervous it would take a long time to resolve, since it was after 6 p.m. when I discovered the issue.I do have a AAA membership, which I’ve primarily used for hotel discounts over the years. However, now I needed help with my car, so I initiated a free service request at 6:10 p.m.Unfortunately, things did not progress from there.At 6:41, I was told (via text) that a driver would be en route soon. 17 minutes later, I was informed that my service had been scheduled, but the online system was still showing nothing. And nearly 90 minutes after submitting the request, I saw that the estimated arrival time would be 9:26 p.m — even though I still had no assigned technician.This, I decided, would be a great time to test out Chase’s roadside assistance benefit. And boy, am I glad I did.How to initiate roadside assistance with a Chase cardTo initiate roadside assistance, call Chase’s card benefits services line. The number is different depending on the card you have, but here are some popular ones:CardNumber to call for roadside assistance<a href=”” target=”_blank”>Chase Sapphire Reserve</a>1-800-350-1697<a href=”” target=”_blank”>Chase Sapphire Reserve for Business℠</a> (see <a href=”/tc/10965?pid=10965&name=Chase%20Sapphire%20Reserve%20for%20Business%E2%84%A0%20PID&data-testid=ratesFees” target=”_blank”>rates and fees</a>)1-800-352-2173<a href=”” target=”_blank”>United℠ Explorer Card</a> (see <a href=”/tc/22035884?pid=22035884&name=United%E2%84%A0%20Explorer%20Card%20PID&data-testid=ratesFees” target=”_blank”>rates and fees</a>)
<p><a href=”” target=”_blank”>United Quest℠ Card</a> (see <a href=”/tc/7752?pid=7752&name=United%20Quest%E2%84%A0%20Card%20PID&data-testid=ratesFees” target=”_blank”>rates and fees</a>)</p>
<p><a href=”” target=”_blank”>United Club℠ Card</a> (see <a href=”/tc/6976?pid=6976&name=United%20Club%E2%84%A0%20Card%20PID&data-testid=ratesFees” target=”_blank”>rates and fees</a>)</p>1-800-350-2919Ritz-Carlton™ Credit Card (no longer available to new applicants)1-800-350-1246Each of these cards covers up to four service calls a year, with a maximum benefit of $50 per call. This typically covers things like a battery test, a tire change, a fuel delivery or a short tow to a repair facility.The information for the Ritz-Carlton Card has been collected independently by The Points Guy. The card details on this page have not been reviewed or provided by the card issuer.Note that many other Chase cards also offer roadside assistance, including the Chase Sapphire Preferred® Card (see rates and fees) — but you’d need to pay “a pre-negotiated, per service fee” to utilize the benefit.When you call, the system will likely ask whether you would like to receive a link to the online claim portal via text, but do not do that. The site is used for most other claims, including car rental coverage and trip delay reimbursement, but not roadside assistance.Instead, follow the prompts to reach a representative about your card benefit, who can help start a service request. Be prepared to enter your full card number and provide some information on what’s going on.You should then receive a text confirming the request with a link to track it.My experience with Chase’s roadside assistanceOnce I got a hold of an agent and gave her my information, the request was officially submitted at 7:37 p.m. Just two minutes later, I got another text, letting me know that a technician had been dispatched and should arrive in 20-50 minutes. So far, a much better timeline than AAA.But I wasn’t prepared for what happened next.At 7:45 p.m., I got an alert on my motion-activated camera, along with a phone call from a local number.The technician had arrived. Eight minutes had elapsed from when I placed the request to when he pulled into my driveway.After accessing my battery and running a test, he quickly determined that I needed a replacement. He had one on his truck, so he went ahead and installed it. He finished by 8:30 p.m.While the service call was free, I did need to cover the cost of the new battery, including labor — but that would’ve been the case regardless of where I took it. The fact that all of it was done within an hour of calling Chase’s benefit services was absolutely astonishing.Bottom lineThe battery in my car recently died, and after nearly an hour and a half waiting for AAA to even dispatch a technician, I decided to test out the roadside assistance service on my Chase Sapphire Reserve. Amazingly, it took just eight minutes for the technician to arrive — and I was finished less than an hour after I placed the request.As it turns out, the technician lives less than two miles from my house, and he just happened to be on call at home when my request came through. That’s clearly a stroke of luck.Nevertheless, it was an important reminder that it’s not just the airport lounge access, statement credits and valuable rewards that matter. Sometimes, those under-the-radar perks can save the day.Editorial disclaimer: Opinions expressed here are the author’s alone, not those of any bank, credit card issuer, airline or hotel chain, and have not been reviewed, approved or otherwise endorsed by any of these entities.
Chattanooga–The Transportation Intermediaries Association (TIA) was quick out of the box earlier this year after two key court decisions that didn’t favor the brokerage community, asking the federal government for some sort of guidance for 3PLs: tell us what sort of carrier hiring practices would protect us. Chris Burroughs is the head of TIA and he told an audience at the FreightWaves Broker Compliance Symposium here on Monday that what the TIA is seeking through its request for a federal rulemaking would take a long time to arrive, earlier efforts having stalled out. “It’s no secret that carrier selection has been problematic for a very long time,” Burroughs said in an interview at the FreightWaves Broker Compliance Symposium here. (Full disclosure: the author of this article conducted the on-stage interview with Burroughs). “I’ve been at TIA for 15 years, and we were having these arguments when I first started that hey, we’ve got to figure out and provide more clarity and eliminate the confusion that exists in the carrier selection process.” The issue is now more stark than ever. While Montgomery vs. Caribe stripped the brokerage community of the liability and negligence protection that had (mostly) been afforded under the Federal Aviation Administration Authorization Act (F4A), it became an even bigger issue not that many weeks later when C.H. Robinson was hit with a more than $600 million nuclear verdict–now at more than $700 million–as a result of a jury award involving a carrier hired by C.H. Robinson (NASDAQ: CHRW) that had a Satisfactory rating from the Federal Motor Carrier Safety Administration (FMCSA). The TIA’s request for a federal rulemaking on the issue occurred between the Montgomery decision and the nuclear verdict in the case of Lipe vs. Lupus Superior. A long history of efforts Burroughs recapped a long list of efforts on the legislative and regulatory side to get some sort of guidance on carrier selection that could be used as part of a courtroom defense. He described negotiations with the association of trial lawyers that would constantly get sidetracked by their opposition as being like Lucy pulling the football away from Charlie Brown. The launch of Commercial, Safety, Accountability scores in 2010 was seen as a way to advance guidance on carrier selection, Burroughs said. “That was supposed to be the answer to tie a data-driven product to a safety rating,” Burroughs said. “Ultimately, that never happened.” Chris Burroughs (l) and John Kingston at FreightWaves’ F3 Broker Compliance Symposium Even the brokerage industry’s desire for changes softened somewhat when the industry began winning some cases through the protection of F4A, Burroughs said. Behind the recent petition for a federal rulemaking, Burroughs said, is saying to FMCSA “hey, you are the federal agency that’s in charge of providing safety ratings to motor carriers. We want you to put forward a federal standard, taking it out of Congress’ hands because of the dysfunction and putting it back in the agency’s hands, where we believe it belongs.” But he added, “rulemaking takes a long time.” Guidance would be a help A more short-term answer might be for FMCSA to issue guidance, Burroughs said. The guidance might say, according to Burroughs, “hey, these are the five or six things, whatever they come up, that should be checked prior to selecting a trucking company, and that would serve as kind of a pseudo carrier selection standard.” FMCSA has a private document of high-risk carriers, Burroughs said. One of the requests TIA has made of the agency is to publish that list as well The brokerage community is also the target of lawsuits filed by plaintiffs who are funded by venture capital companies. (It was discussed how Paul Clement, who represented Shawn Montgomery before the Supreme Court, is the “Michael Jordan” of attorneys who argue before the high court. Burroughs declined with a smile to estimate on what Clement was getting paid by the hour). “They’re seeing blood in the water,” Burroughs said. Tough choices to be made The quandary that C.H. Robinson now faces in Lipe vs. Lupus Superior is that the ruling was not only expensive. It also involved a finding that the driver in the crash, who was killed, was essentially a C.H. Robinson employee. That sort of ruling, if it established a precedent, would open the door to even greater litigation hitting brokers. But the clock is ticking at an annual rate of more than 6% interest on the now $700-million judgement which began at $603 million. A settlement would end the process but leave the finding about the driver’s relationship to C.H. Robinson intact. Burroughs said C.H. Robinson’s strategy is clear: it is going to fight the verdict and not settle the case, which came out of a Dallas County courthouse. “I’ve talked to (C.H. Robinson CEO) Dave Bozeman and (chief legal officer) Dorothy Capers,” Burroughs said. “They’re clearly going through the appeal process. They’re not going to settle the case.” He also expressed confidence based on those conversations that C.H. Robinson can win on appeal. Better news on insurance One of the potential negative impacts from the dual hits of Montgomery and Lipe was expected to be seen in insurance rates paid by brokers. Burroughs said soon after the decision, “there was a two to four week period where rates were extremely high in terms of renewal.” Much of that was timing, he added; TIA members who renewed just before that period “hit the lottery.” But that trend has calmed, according to Burroughts. “We’re not seeing any sort of massive, drastic increase in terms of insurance rates at double digits,” he said. More articles by John Kingston English language rule’s comments bring criticism from Sikh organization FMCSA’s Elison addresses Motus again, still no date on full repair CEO’s letter boasts of lots of arrows pointing up at Triumph Financial The post Federal guidance on carrier selection not around the corner: TIA’s Burroughs appeared first on FreightWaves.
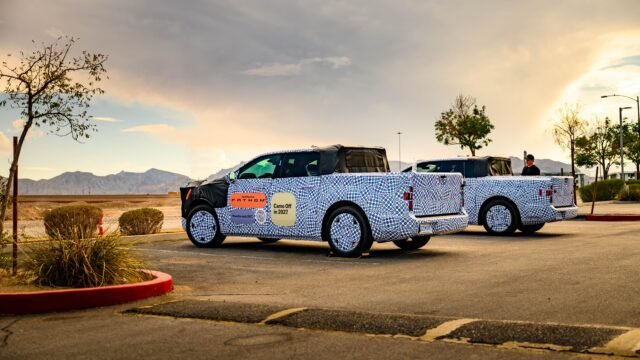
We're still a few months away from the official reveal of the Ford Fathom, the automaker's first next-generation electric vehicle. While we wait, Ford has been whetting our appetite with news about the sub-$30,000 pickup - including today's announcement about the Fathom's bidirectional charging capabilities. With an increasing number of EVs coming out with bidirectional vehicle-to-home (V2H) or vehicle-to-load (V2L) charging capabilities, Ford is trying to position the Fathom as a key entrant - and one that simplifies the system by making it an everyday reality rather than a $10,000 luxury perk. Unlike the discontinued F-150 Lightning, wh … Read the full story at The Verge.
The way courts decide who is responsible when a contracted truck ends up in a wreck is changing faster than most of the freight industry realizes, and the shift is not about one ruling or one eye-popping dollar figure, it is a whole direction of travel that keeps pulling responsibility up the chain toward brokers and the companies that arrange freight, a change that one transportation attorney recently laid out in detail for a room full of freight professionals who sit squarely in its blast radius. The attorney, Matthew Leffler, an adjunct law professor at Michigan State University College of Law who goes by The Armchair Attorney and has practiced for 16 years, was blunt about the stakes. Fielding live questions at a town-hall session of the FreightWaves Freight Brokerage Compliance Symposium, he ranged across broker liability after Montgomery, nuclear verdicts, FMCSA enforcement, carrier vetting, drop-trailer strategy, and the newer category of AI-driven risk, but the thread tying all of it together was one warning. He argued that what is happening right now on the liability front is as profound a shift for freight as deregulation was in the late 1970s, maybe as profound as containerization, and that ten years from now the business will look almost unrecognizable because of the legal pressure building on it. None of what follows is legal advice, and Leffler said as much repeatedly, but the picture he painted and the practical guidance he offered are worth every broker and every small carrier understanding in detail. The Case That Changes The Math The facts, as Leffler described them, are ordinary right up until they are catastrophic. A broker worked with a shipper, sourced a carrier called Lupus Superior, and the carrier moved the load. That carrier held a satisfactory safety rating, which is rarer than most people think, because by Leffler’s count roughly 94 percent of trucking companies carry no safety rating at all, not satisfactory, not conditional, not unsatisfactory. On paper this was about as good a carrier as a broker could ask for. Then the human element broke the chain. By Leffler’s account of the trial evidence, the driver told his dispatcher he was not feeling well, the dispatcher relayed that to the broker, C.H. Robinson, and the question of whether to swap in another driver came up. For reasons that may never be fully clear, the sick driver took the load anyway. The truck hit stopped traffic on Interstate 20 in Mississippi, and the fire that followed killed three people, seriously injured two more, and killed the driver himself. The lawsuit named the driver, the carrier, and the broker. window.googletag = window.googletag || {cmd: []}; googletag.cmd.push(function() { var gptSlot = googletag.defineSlot('/21776187881/FW-Responsive-Main_Content-Slot1', [[300, 100], [320, 50], [728, 90], [468, 60]], 'div-gpt-ad-1709668545404-0').defineSizeMapping(gptSizeMaps.banner1).addService(googletag.pubads()); googletag.pubads().enableSingleRequest(); googletag.pubads().collapseEmptyDivs(); googletag.enableServices(); setInterval(function() { if (!document.hidden) { googletag.pubads().refresh([gptSlot]); } }, 60000); }); googletag.cmd.push(function() { googletag.display('div-gpt-ad-1709668545404-0'); }); Here is where Leffler said brokers need to pay close attention, because two separate strands drove the outcome. The first was ordinary negligence tied to carrier selection, the kind of claim Montgomery made familiar, though the picture here is murkier than a clean selection verdict, since the jury actually answered no to one broker-negligence question and its general negligence finding only left room for a selection theory rather than squarely resting on one. What is not in dispute is the number, because the jury found the broker 23 percent negligent on a 604 million dollar award, which is already staggering. The second strand is the one that should keep brokers up at night, vicarious liability, the old principle of respondeat superior, let the master answer. The plaintiffs argued, and the jury agreed, that the broker had exercised enough control to make the driver effectively its own borrowed employee. Once that happened, the driver’s own negligence, which the jury put at 45 percent, got stacked onto the broker’s share. That brings the broker to 68 percent. And in Texas, where liability over 50 percent triggers joint-and-several liability, being 68 percent responsible means being on the hook for the entire amount. It is worth being precise about where this stands, because no final judgment has been entered. C.H. Robinson has characterized the July 23 result as an advisory verdict that is still subject to post-trial proceedings, and the company has said it will appeal. Leffler’s point was that this is not a narrow, one-off result. If the borrowed-employee theory holds up through appeal, the entire premise of brokerage, that you arrange transportation using carriers who are not your employees, is in question, and by extension so is the model behind companies like FedEx Ground, Amazon’s delivery network, Uber, and DoorDash, all of which exert far more control over their drivers than C.H. Robinson ever did here. He expects the case to be litigated for five or six years, all the way to the Texas Supreme Court, with no clean way around it in the meantime. Why A Tracking App Became A Liability The detail that turned control from an abstraction into evidence was technology. Leffler explained that C.H. Robinson used a proprietary application to track the load, and the plaintiffs convinced the jury that an app living on the driver’s phone for that shipment looked a lot like control, a lot like the driver was furthering the broker’s business, which supported treating him as a borrowed employee. Leffler was candid that he personally thinks the distinction should be legally irrelevant, that a tracking app tells you when freight will arrive and does not actually direct how a driver drives. But he was equally clear that what should matter and what a jury believes are two different things, especially when that jury has just watched dashcam video of a person burning to death. His hard-earned takeaways were specific. He said he would never use a proprietary tracking app again, because all a plaintiff attorney has to do is convince a jury that the app the broker built controls the driver, and most jurors do not understand how the technology actually works. He urged using third-party telematics platforms rather than homegrown tools, framing the data as tracking the load rather than the driver. And he stressed that language matters, that a broker should talk about being contracted with a carrier, never about having hired a driver, because word choice becomes exhibit text in a courtroom. The Wave Is Bigger Than One Case To show what juries are willing to do, Leffler pointed to the Werner Enterprises case, where a truck traveling under the speed limit in icy conditions was struck by another vehicle that crossed a wide median, and the jury still found Werner 70 percent responsible for a 90 million dollar award even though the Werner driver had done little wrong. The appellate story matters as much as the verdict, though, because the Texas Supreme Court reversed and dismissed that result in June 2025, finding that Werner’s truck was not a legal cause of the crash. The same court went the industry’s way again on May 15, 2026, in the matter involving Home Depot, holding that a shipper that simply hands freight to a federally registered carrier owes no duty to the motoring public and ordering the negligent-selection claims dismissed, a point Leffler has made in his own writing. Read together the pair shows a system pulling in two directions at once, juries willing to assign enormous liability and at least one state’s highest court willing to claw it back, which is exactly the kind of uncertainty that makes planning so hard. The economics explain why this keeps happening. Leffler described a plaintiff’s bar that treats freight as a gold mine, working on contingency fees around 33 percent, now backed by litigation-funding investors who buy a stake in the eventual recovery, which gives plaintiff attorneys the budget to run a dozen mock trials where a defense firm might manage one. He reminded the room that civil cases turn on preponderance of the evidence, just 51 percent, not the criminal standard of beyond a reasonable doubt, so a jury only has to believe you are slightly more likely wrong than right. Meanwhile the structural backdrop is ugly, with the federal minimum carrier liability insurance still sitting at 750,000 dollars, a number set back in the 1980s, a national out-of-service rate around 22 percent for commercial vehicles, and brokers now moving close to 30 percent of the nation’s freight. Underinsured carriers, deferred maintenance, and a public that has no idea how any of this works add up to an environment where even winning can cost millions and years. The Survival Playbook Leffler is not a fatalist, and he closed with concrete guidance that brokers should validate with their own outside counsel and insurers. The centerpiece is a written policy that gets updated regularly and, above all, gets enforced rigidly. His warning was that a great policy you do not follow is worse than no policy at all, because the moment you deviate from it on the load that ends in a fatality, a plaintiff attorney will hold up your own written standard and tell the jury you lied. He was unsentimental about enforcement, saying that if people deviate from the written process you write them up, and if they keep doing it you let them go, because a single person freelancing at 2 a.m. on a Saturday can sink the company. window.googletag = window.googletag || {cmd: []}; googletag.cmd.push(function() { var gptSlot = googletag.defineSlot('/21776187881/fw-responsive-main_content-slot3', [[728, 90], [468, 60], [320, 50], [300, 100]], 'div-gpt-ad-1665767553440-0').defineSizeMapping(gptSizeMaps.banner1).addService(googletag.pubads()); googletag.pubads().enableSingleRequest(); googletag.pubads().collapseEmptyDivs(); googletag.enableServices(); setInterval(function() { if (!document.hidden) { googletag.pubads().refresh([gptSlot]); } }, 60000); }); googletag.cmd.push(function() { googletag.display('div-gpt-ad-1665767553440-0'); }); The rest of his advice followed the same logic of limiting control and controlling information. Route all communication through dispatch and avoid speaking directly to drivers whenever a carrier has a dispatcher, because direct driver contact opens the door to knowledge you do not want, like learning a driver is unwell and then being blamed for letting them roll. Understand that indemnification clauses in shipper contracts only protect you if you are still solvent when the litigation ends, so an indemnity from a bankrupt broker is worthless. Carry real liability coverage beyond the mandatory 75,000 dollar surety bond, including contingent auto and cargo protection, because fighting one of these cases without insurance can run 20,000 to 30,000 dollars a month. And assume that every record in your transportation management system will be discovered and read back to a jury, so the metadata trail needs to match the policy you claim to follow. Leffler was honest about the bind this creates, that following every rule to the letter can leave a broker at a competitive disadvantage against those who cut corners, and that the pressure to keep a long-trusted carrier or customer moving is real. His answer was that brokers and small carriers are not adversaries in this, they exist because of each other, and the real winners of this liability wave are the large asset-based carriers who have carried this kind of exposure for decades and simply raise their insurance towers and move on. The operators most exposed are the small brokers and small carriers who can least afford a single catastrophic claim. Why It Matters A jury’s 604 million dollar finding against a broker over ordinary brokering, with a clean carrier and a routine tracking app and before any final judgment has even been entered, tells every broker and the small carriers they depend on that the old assumption of being insulated from a crash several steps down the chain is gone, and that control, communication, and documentation are now the difference between surviving a claim and being bankrupted by one. The practical response is not to panic but to build and rigidly enforce a written compliance process, rethink proprietary tracking and direct driver contact, and carry enough real insurance to still be standing when the litigation ends, because in this environment the goal is not only to do everything right but to be able to prove it years later in front of a jury that does not care how freight moves. This article is based on a town-hall session with attorney Matthew Leffler, an adjunct professor at Michigan State University College of Law known as The Armchair Attorney, at the FreightWaves Freight Brokerage Compliance Symposium. Case details, figures, and guidance are as presented by the speaker and reflect his analysis, not legal advice. The C.H. Robinson result is an advisory verdict subject to post-trial proceedings and appeal, with no final judgment entered. The Werner and Home Depot verdicts referenced were later reversed by the Texas Supreme Court. window.googletag = window.googletag || {cmd: []}; googletag.cmd.push(function() { var gptSlot = googletag.defineSlot('/21776187881/fw-responsive-main_content-slot4', [[300, 100], [320, 50], [728, 90], [468, 60]], 'div-gpt-ad-1709668086344-0').defineSizeMapping(gptSizeMaps.banner1).addService(googletag.pubads()); googletag.pubads().enableSingleRequest(); googletag.pubads().collapseEmptyDivs(); googletag.enableServices(); setInterval(function() { if (!document.hidden) { googletag.pubads().refresh([gptSlot]); } }, 60000); }); googletag.cmd.push(function() { googletag.display('div-gpt-ad-1709668086344-0'); }); The post The Biggest Shift In Freight Liability Since Deregulation Is Here, And Few Are Ready For It appeared first on FreightWaves.